Sign up

PLUM INTEREST
EARN UP TO 3.94% VAR*

Plum Interest

Earn returns every day with Plum Interest, a low-risk money market investment fund holding government-backed assets.

Sign up for free in just a few taps.

Join Now

*Variate annual rate correct as at 02/07/2025 and applicable to Max users. Learn more about our subscriptions here. Plum Interest is an investment product, so you could get back less than you put in. Forecasts are not a reliable indicator of future performance.

Don’t let your money go idle

Plum Interest Open Icon

Your money is invested in an interest-earning fund holding government-backed assets.

Plum Interest Get Returns Icon

With daily returns, your progress is updated regularly instead of 
just once a month or even once a year.

Plum Interest Easy Access Icon

You can continue using your money as normal with 1-business day withdrawals, giving you even greater control over your money.

Add money automatically

You can balance all your financial goals by automatically dividing your money between Plum Interest and your other investments or easy access savings.


It's a great way to save you time and keep your strategy on track when you’re busy. However, you should periodically review whether your decisions are still suitable, given your current circumstances.


Add Money Image

It’s time to get growing

Rising interest rates are great for savers, but that’s only if banks choose to pass it on to your account. 


Instead of waiting around, you could be earning a rate much closer to that of the Bank of England with Plum Interest.

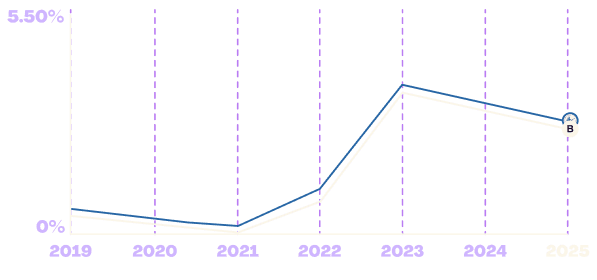
UK updated Plum Interest Graph 2025

Plum Interest is held in the BlackRock ICS Sterling Government Liquidity Fund. This graph is showing the past performance of the last 7 years, excluding Plum fees. Keep in mind that past performance is not a reliable indicator of future results.


Visit the Fund's page for more information.

How your money’s protected

When you use Plum Interest, your money is held in a Qualifying Money Market Fund (QMMF). Financial institutions use these funds to manage large amounts of cash because they focus on short-term UK government-backed assets like bonds.


QMMFs are protected under FCA rules for “Safe Custody,” meaning your money is kept in a separate, secure account, away from Plum’s or the fund provider’s assets. In the unlikely event of insolvency of Plum, the fund manager, or fund custodian, your funds would be returned to you, unless the fund manager or custodian had breached Safe Custody rules fraudulently. 


In that scenario, your Plum Interest funds would be returned through the provisions of FSCS protection up to £85,000. FSCS would not cover a loss that comes from a fall in the market value of the QMMF units. 


Read more about how your money's protected.


Easy Access Image

The 3.94%* annual variable return we provide is a net rate. That means the rate we show you already includes our 0.25% annual fee, based on the daily balance that you hold in Plum Interest, so you know exactly what you're getting. That fee is how Plum keeps its light on. Learn more here.

A Plum Subscription unlocks more

When you subscribe to Plum, you get a boost on your Plum Interest rate.

Plum Basic (our free tier) gets your 3.01% VAR. With Plum Plus (£3.99/month), you can get 3.47% VAR, with Boost (£7.99/month) 3.75%, and with Plum Max (£14.99/month) you'll get 3.94%.


Returns vary depending on your subscription. If you use a Plum subscription just for higher returns, but don't deposit enough to cover your subscription fee, you could earn less than you gain.

Explore subscriptions
Choose your Plum subscription

Did we miss anything?

Here are a few questions people sometimes ask before they join us.

Plum Interest allows you to invest in bonds issued by the government. It also makes short-term loans to robust companies, who can show a strong track record, in exchange for government bonds.


That means those assets are backed by the government, and you can earn a share of any interest earned, with less risk than other types of investments.

If you add money to your Plum Interest Pocket, you'll be charged a yearly fee depending on your Plum subscription and based on the daily balance that you hold in the fund. Keep in mind that rates shown in the Plum app are already net of fees.

We waive the annual fee for Plum Max subscribers, so they don't have to pay it.

Plum Boost subscribers are charged an annual service charge fee of 0.19% by Plum, based on the daily balance held in the fund.

Plum Plus subscribers are charged an annual service charge fee of 0.47% by Plum, based on the daily balance held in the fund.

Plum Basic customers without a subscription are charged an annual service fee of 0.93% by Plum, based on the daily balance in the fund.

All customers must pay a 0.10% fund management fee for BlackRock. The fund value is automatically updated to reflect BlackRock's fee, so you won't see it as a separate charge.

Plum's service fee, if any, will be calculated daily based on the balance you hold in your fund and collected monthly.


Learn more about fees for investing with Plum.

The fund manager for Plum Interest is BlackRock, an investment company with global presence.


Money placed in Plum Interest is invested in units of a Qualifying Money Market Fund (QMMF), rather than held as cash on deposit. 


These units are protected under the FCA’s CASS rules, also known as “Safe Custody” when it comes to assets. These rules mean they are placed into a separate, segregated account away from the fund provider’s own assets or Plum’s own assets.


Therefore, in the unlikely instance where Plum, the fund manager, or the custodian goes insolvent, your funds would be returned to you, unless the fund manager or custodian had breached Safe Custody rules fraudulently. 


In that scenario, your Plum Interest funds would be returned through the provisions of FSCS protection up to £85,000. FSCS would not cover a loss that comes from a fall in the market value of the QMMF units.


This is a projection of the rate at which your money could grow over the next year. To keep things simple, we quote the net yield (after fees are applied).


The projection is based on the 1-day yield, which means it takes the previous day’s return and scales this to reflect what the fund could earn over a full calendar year. The actual rate offered in each market is similar to the base rate set by the central bank (the Bank of England in the UK), which can fluctuate over time.

On the scale of investment risk, this fund can be considered amongst the lowest available. That’s because it invests in high quality assets, like government bonds, and only loans money on a short-term basis to reputable companies and governments.


There is a risk that the forecast of projected yield might not be fulfilled over a longer period e.g. if the central bank lowers its base rate over time. But this fund is designed to transact at a constant price, so you shouldn’t get back less than the initial principal you invested, in the short term.

Yes, firstly, you must move the money into your Plum Primary Pocket. From here, you can then withdraw to your linked bank account.

To do this, tap the ‘Pockets’ menu button, then the ‘Plum Interest’ tab and finally ‘Move’. We’ll show an estimated settlement date in the app when you request a movement. Movements are typically processed within 1 working day, with sell orders settled Mon–Fri at around 09:30 a.m. (UK time).

Once your movement has been processed, the money will be credited to your Primary Pocket balance. You can then withdraw to your bank in the same day.

There are no limits or additional fees to withdraw from Plum Interest. And we plan to introduce instant withdrawals soon!


Let’s get started

Join over 2 million people who've downloaded Plum.

Get Started Image
Download app on apple appstoreDownload app on android play store